JP Morgan Sees Strong Q2 for Marina Bay Sands
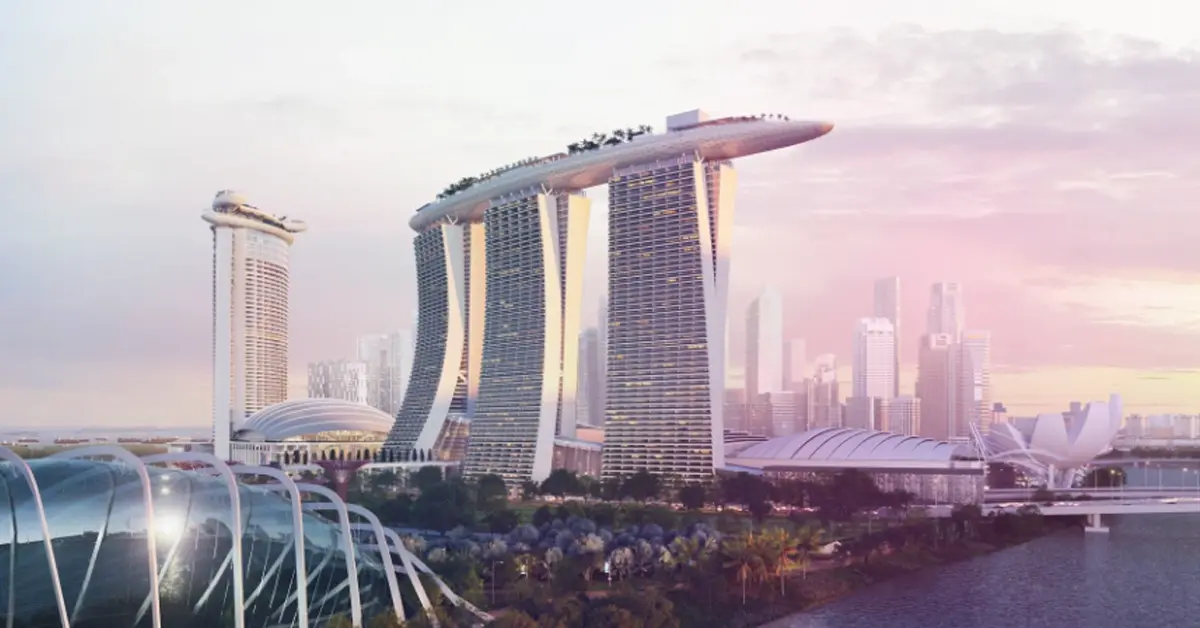
JP Morgan Securities LLC expects Marina Bay Sands to report property-level EBITDA of approximately US$727 million for the second quarter, representing a 5% decline compared with the same period last year. Despite the projected decrease, the brokerage said the result would remain broadly in line with market expectations and reflect the continued strength of Singapore’s flagship integrated resort.
Forecast Remains Close to Market Expectations
In a research note released on Wednesday, JP Morgan analysts Daniel Politzer, Samuel Nielsen and Michael Hirsh estimated second-quarter EBITDA at US$727 million, closely matching the market consensus of around US$725 million.
While the projection suggests lower profitability than a year earlier, the brokerage expects revenue to continue growing. Marina Bay Sands, one of Singapore’s two integrated resorts, is operated by Las Vegas Sands Corp, the parent company of Macau-based Sands China Ltd.
According to the analysts, the second quarter is likely to show continued revenue growth, although earnings are expected to soften compared with the strong performance recorded in the prior-year period.
Premium Strategy Continues to Support Performance
JP Morgan attributed Marina Bay Sands’ resilient performance to sustained premium demand, supported by Las Vegas Sands’ ongoing investment strategy and increasing consumer spending power in Singapore.
The resort delivered strong first-quarter results, posting nearly US$1.49 billion in net revenue, compared with US$1.16 billion a year earlier. Adjusted property EBITDA reached US$788 million, reflecting a 30.3% year-on-year increase.
Those results provide the context for the second-quarter forecast, with JP Morgan suggesting that the property continues to benefit from stronger demand despite facing tougher year-on-year comparisons.
Expansion Plans Remain on Track
Las Vegas Sands is continuing work on the US$8 billion Marina Bay Sands expansion project, commonly known as MBS 2.0, which is expected to be completed in 2030.
The development is intended to reinforce the resort’s long-term position in Singapore’s gaming and hospitality market. JP Morgan’s analysis indicates that, despite a modest decline in quarterly EBITDA, Marina Bay Sands remains a key earnings driver for the group, supported by premium customer demand and significant future investment.
Long-Term Outlook Unchanged
Although second-quarter EBITDA is forecast to decline by 5% year-on-year, JP Morgan believes the property continues to demonstrate strong operating performance. Revenue is still expected to increase compared with the same period last year, highlighting the resort’s resilience as it prepares for its next phase of expansion.
iGamist Editorial Team
An experienced writer covering the latest trends in online gaming and iGaming industry.
Stay Updated
Get the latest iGaming news and guides delivered to your inbox